102 million people, one real-time economy: how Vietnam is building the next generation of banking

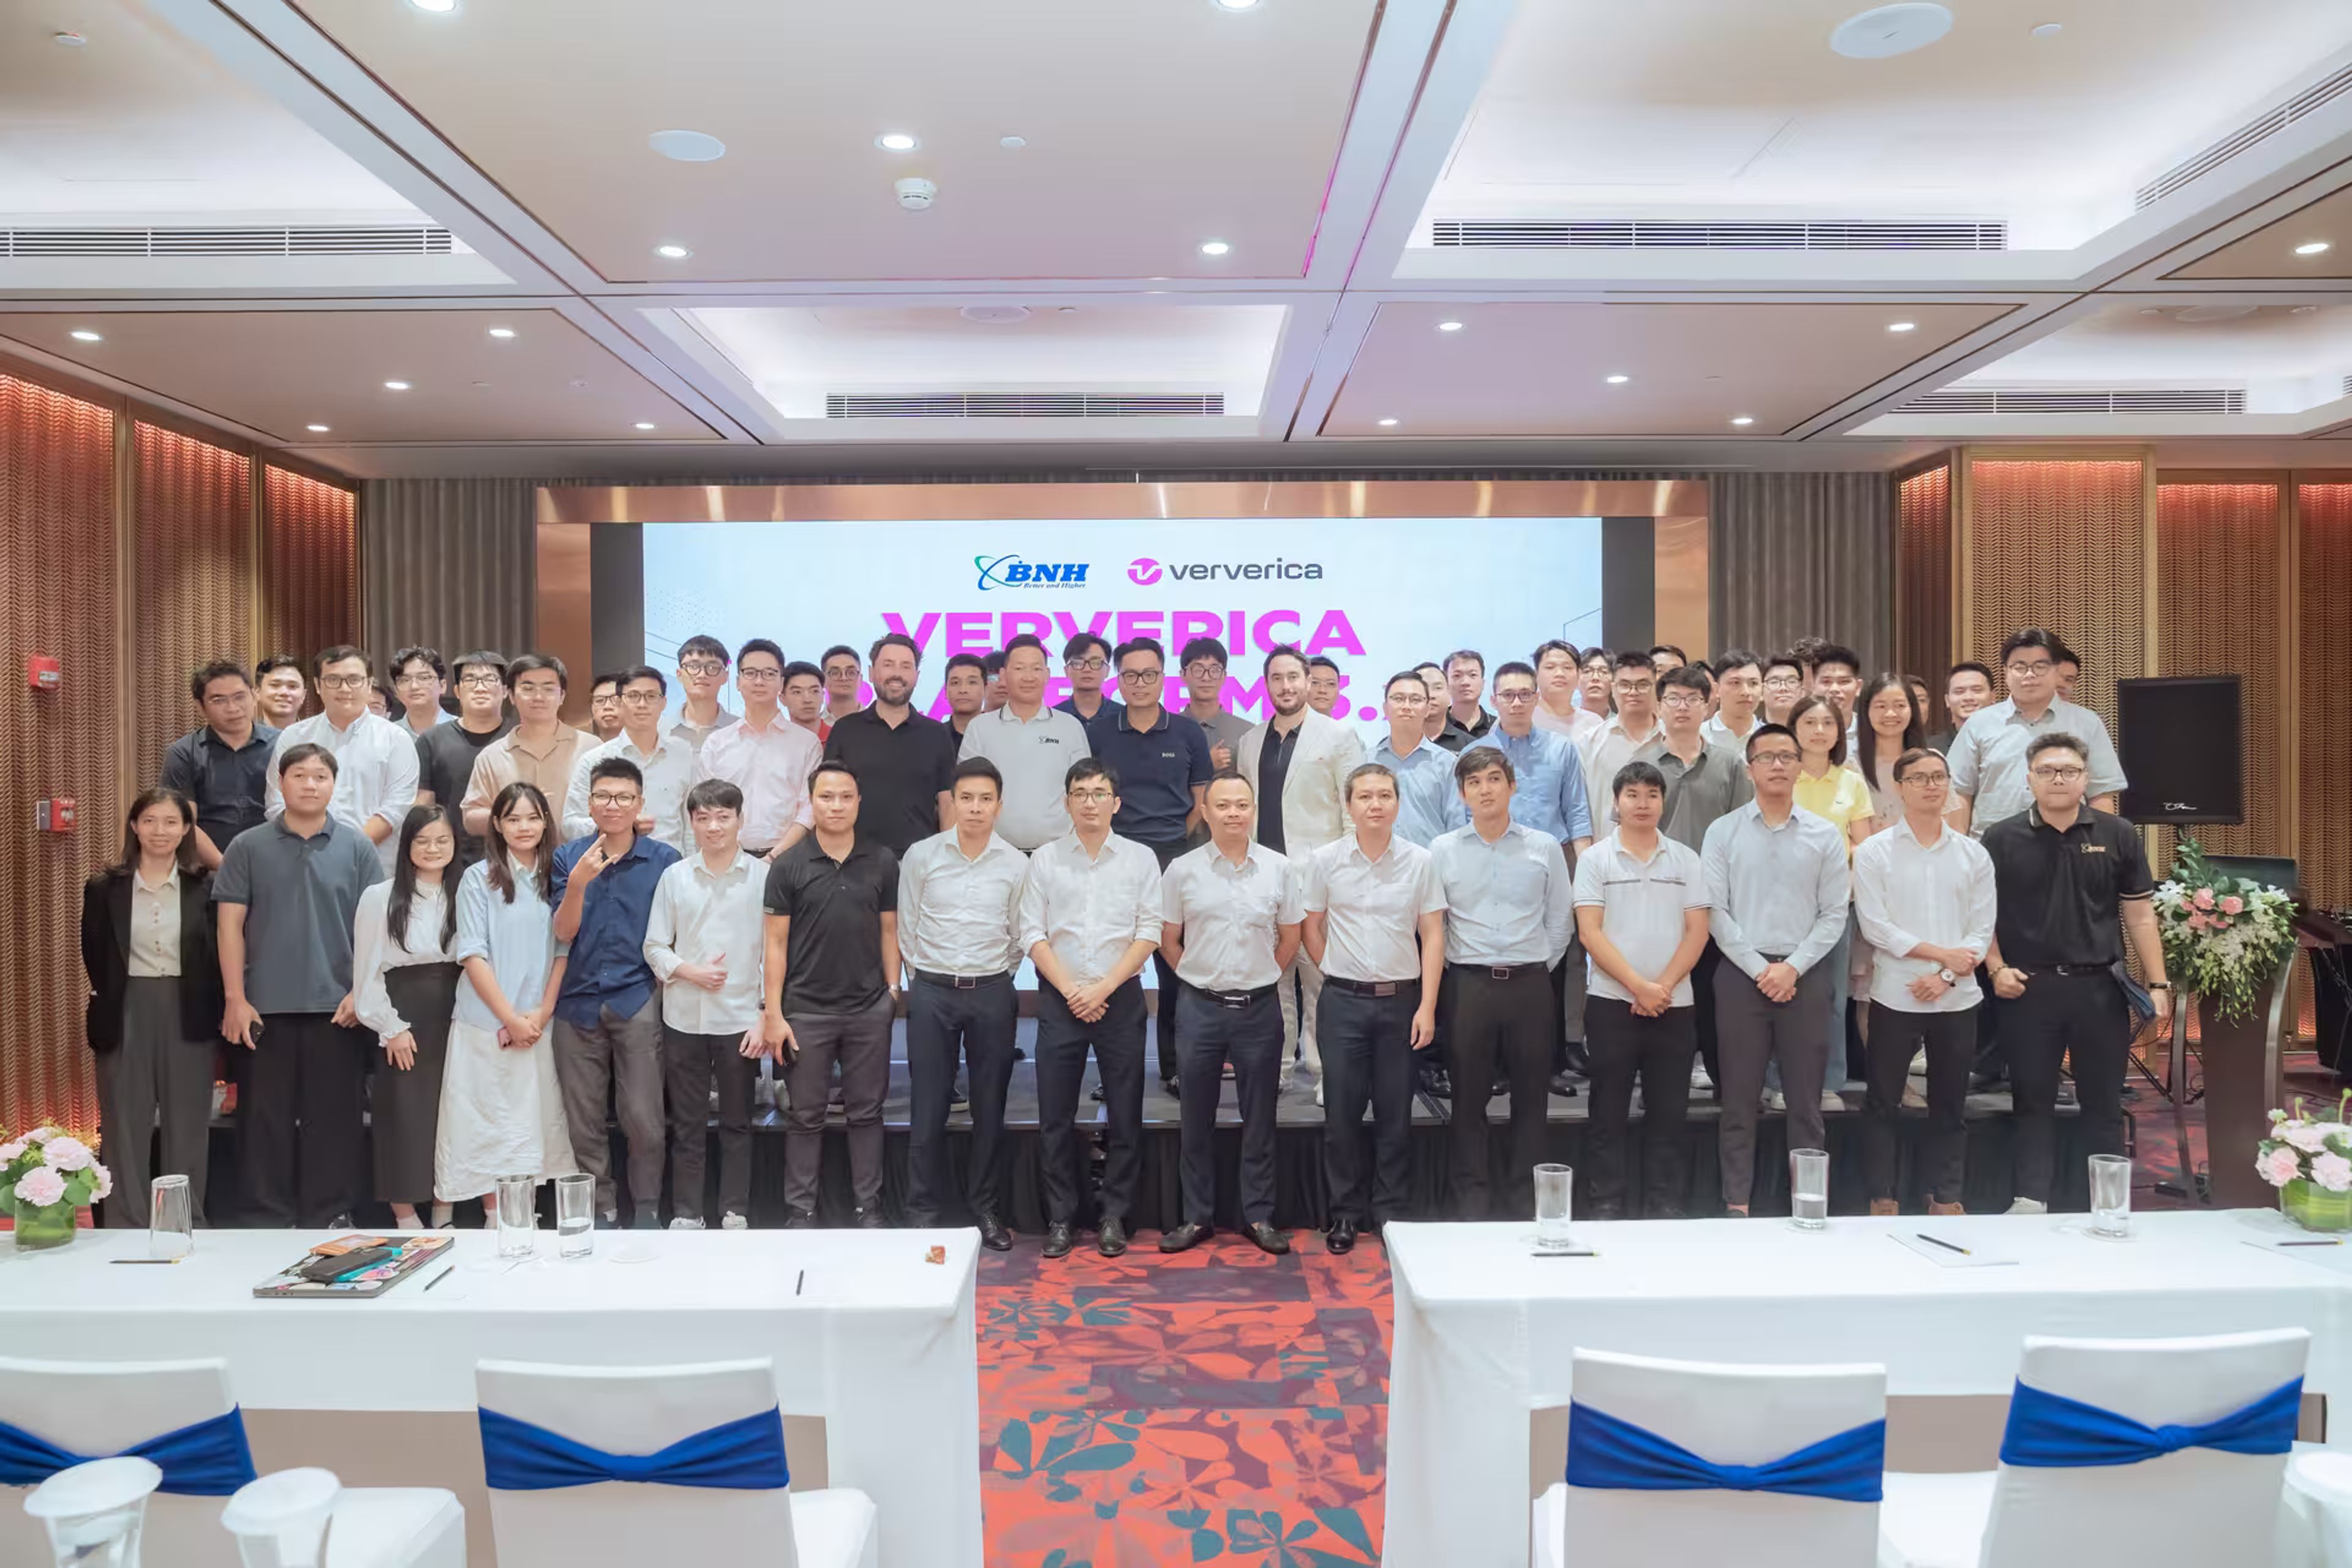
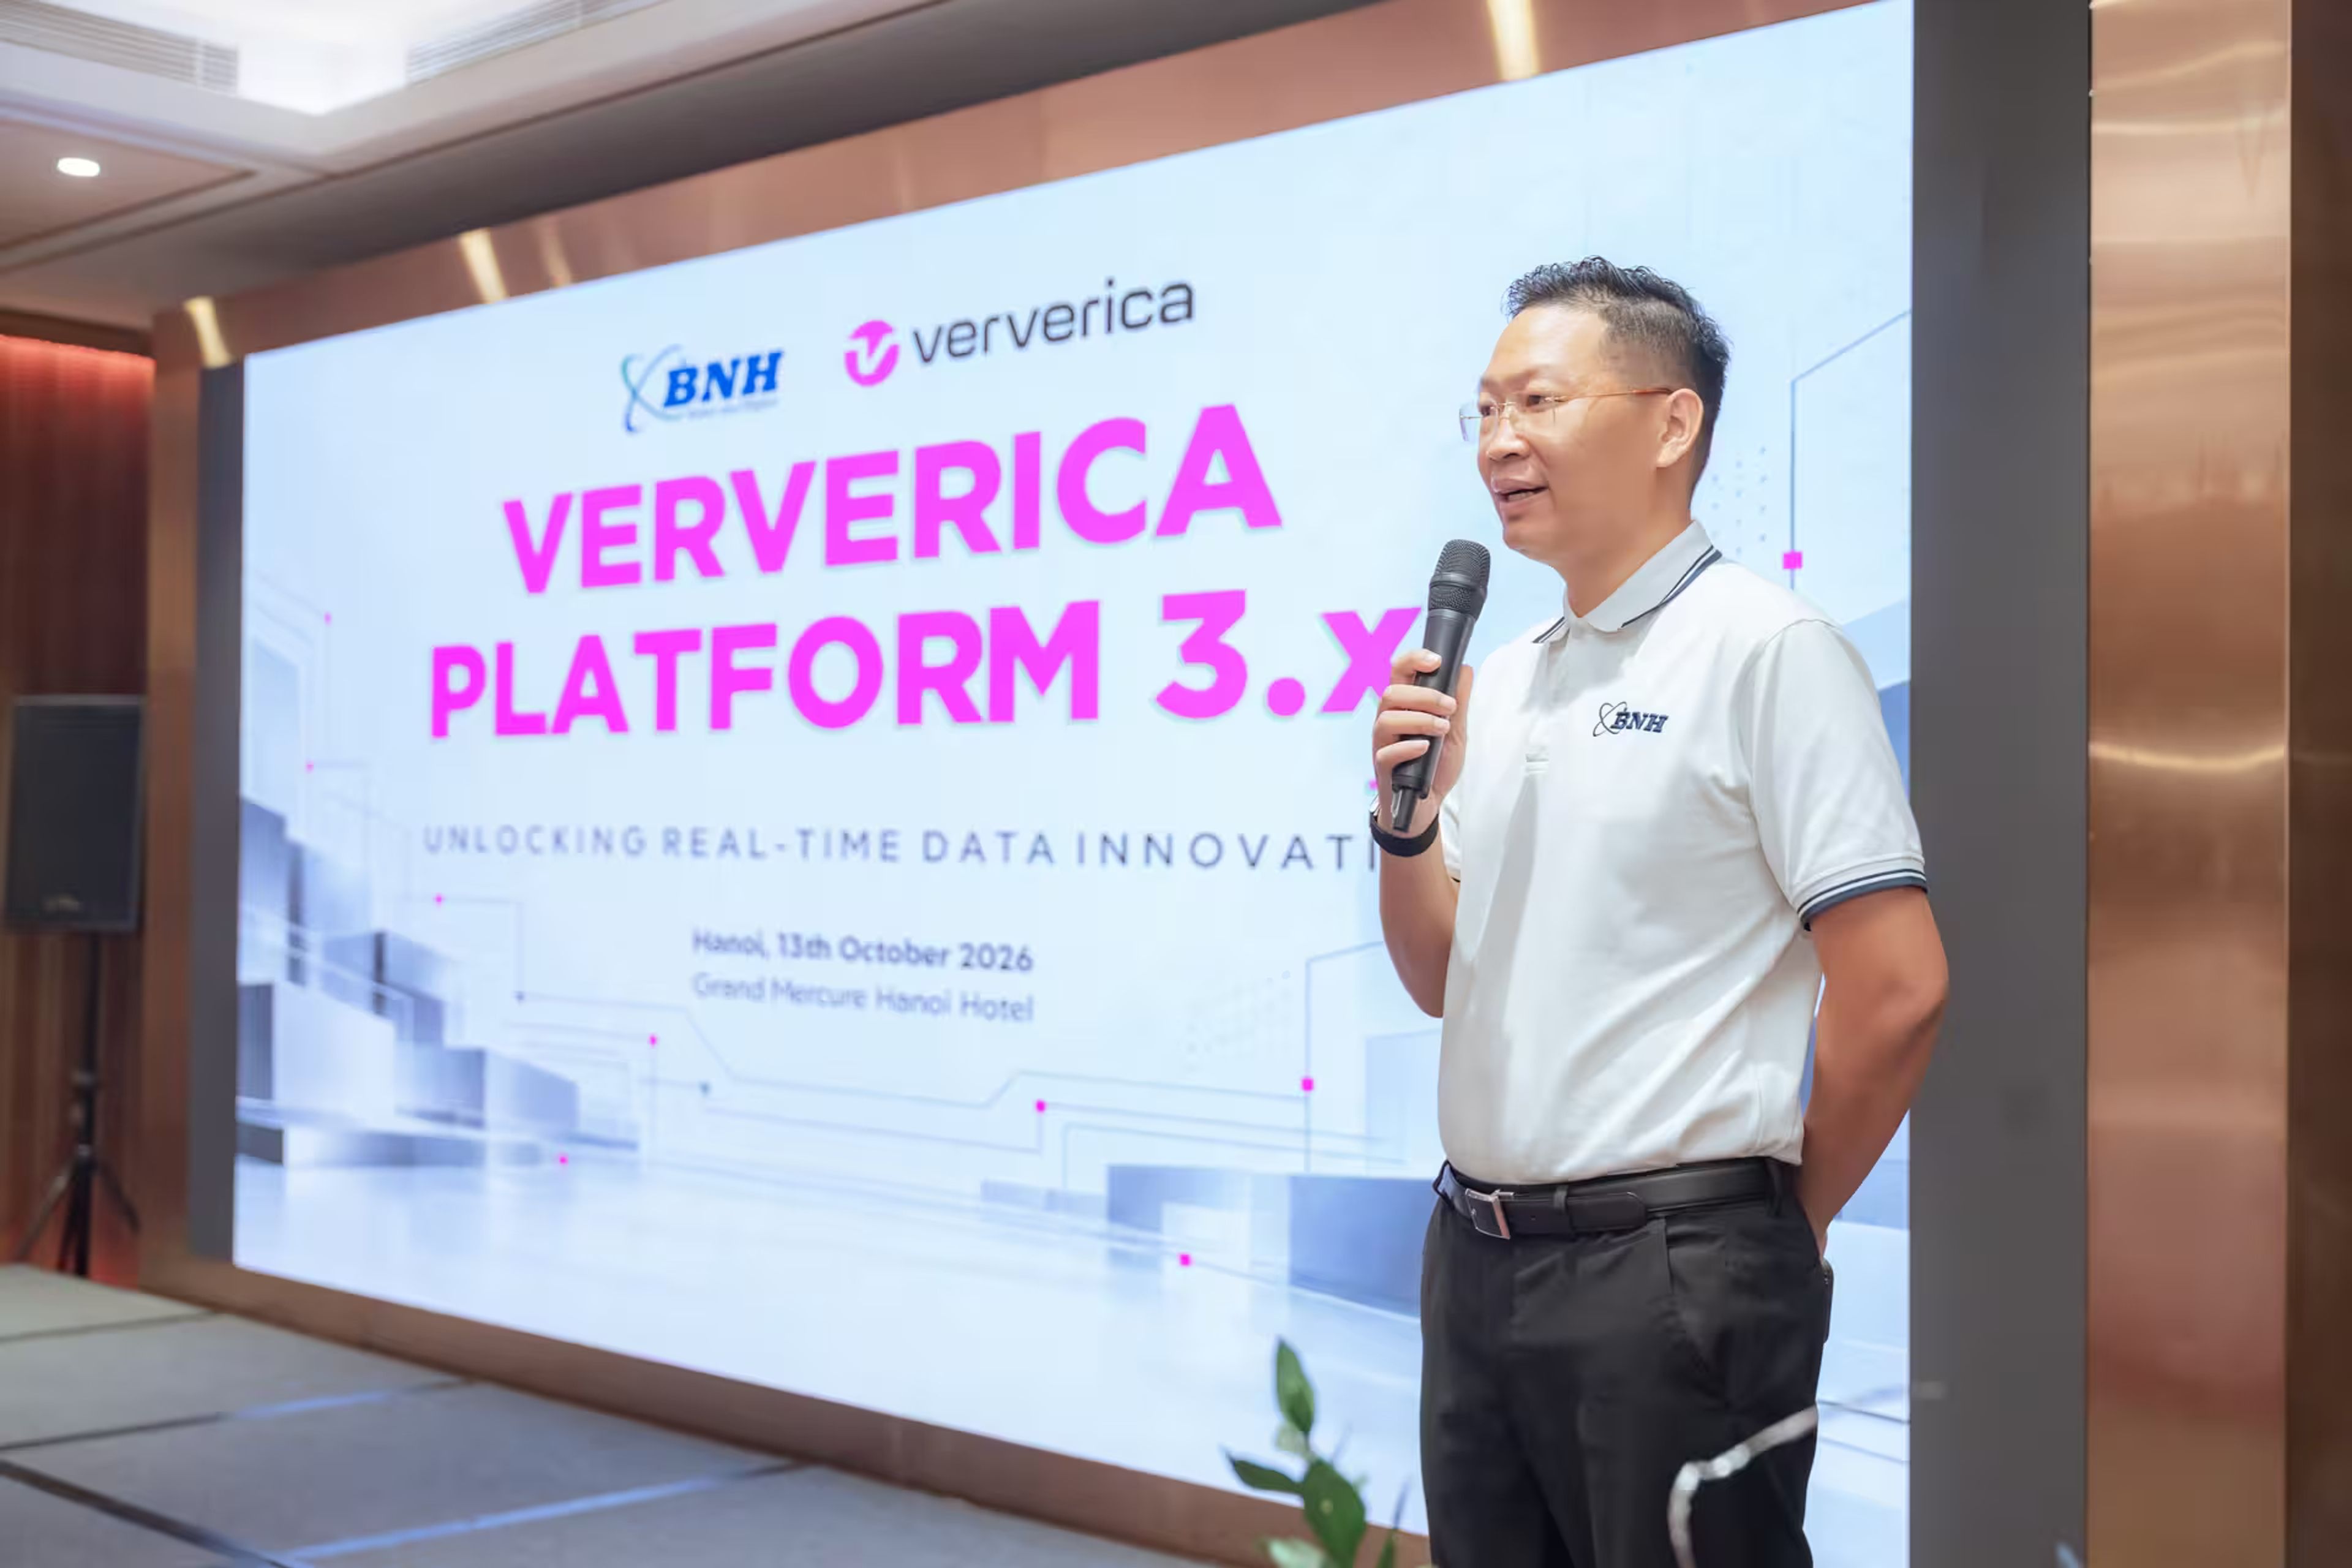
On October 13th, our partner BNH brought together over 60 banking and technology leaders in Hanoi to talk about where real-time data is going and what technological leadership means for the institutions that move money in this country. My colleague Chris Horsnell and myself had the honor of representing Ververica at the seminar and witnessed the speed of innovation firsthand. This is the short version, written from two seats: Ververica, which builds the streaming platform, and BNH, which delivers it in Vietnam.
A country that already runs in real time
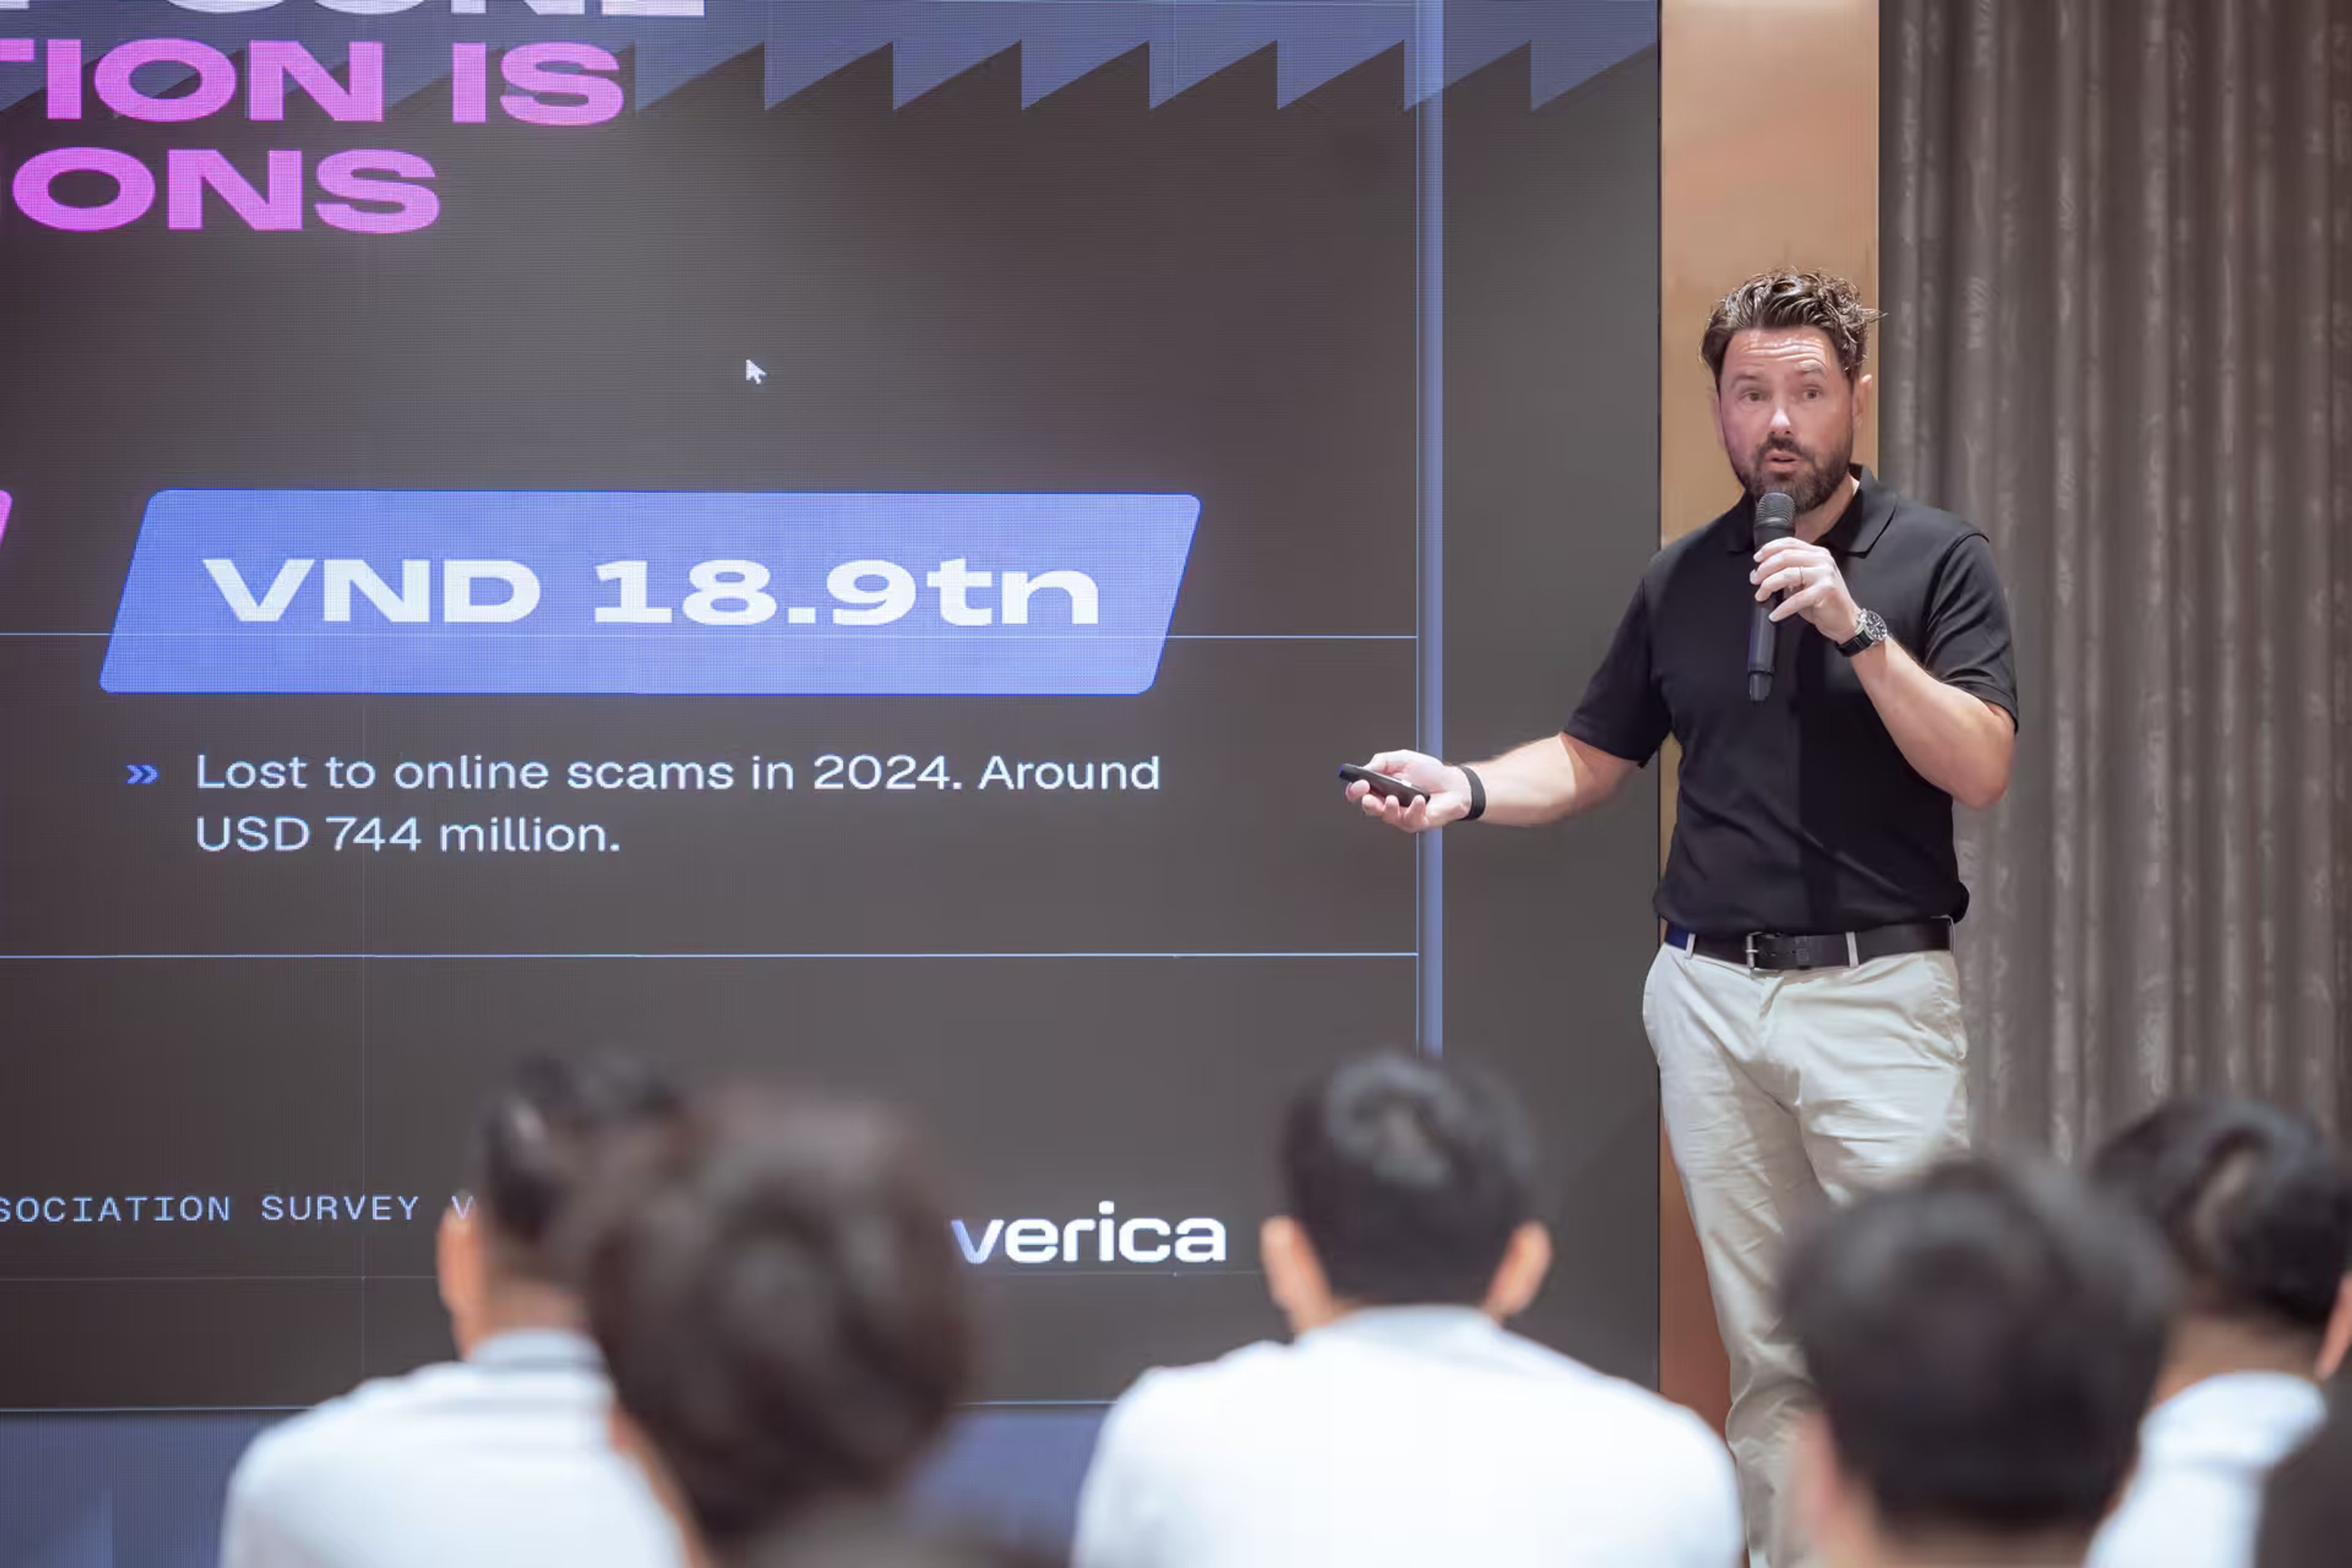
Vietnam is big. It is home to over 102 million people, significantly more than the UK, Germany or France. Nearly 90% of adults hold a bank account, and almost the whole country accesses their bank through their phone. Actually, many banks run more than 95% of transactions through digital channels.
Vietnam is also very digitally advanced, and adopts innovation at a world-leading pace. For example, over 90% of Vietnamese consumers use a mobile wallet, second-most in the world. For context, the same research puts the United States on 33rd place for adoption of mobile wallets and real-time payments. By mid-2026, cashless payments were worth about 28 times GDP. And Vietnam has the highest AI use in Southeast Asia: 81% of users interact with AI tools and features daily.
The next race: the data behind every decision.
Vietnam has solved the hardest problem in digital banking, which is persuading a hundred million people to trust a screen with their money. A VietQR payment or a biometric check on a large transfer now complete in seconds. The regulator has gone further than most of its peers: SIMO links 149 institutions into a shared view of suspicious accounts that updates as money moves, and the Credit Information Center (CIC) provides a single source for creditworthiness data of all individuals and businesses.
However, most banks still reason about their customers on a delay. Fraud models score against profiles refreshed overnight. Anti-money-laundering backtests run on a separate copy of the data, refreshed in batch. Regulatory reports are assembled after the fact. For the past decades, that delay was an accepted cost of doing business, but it is quickly becoming the main constraint on what a bank can do next.
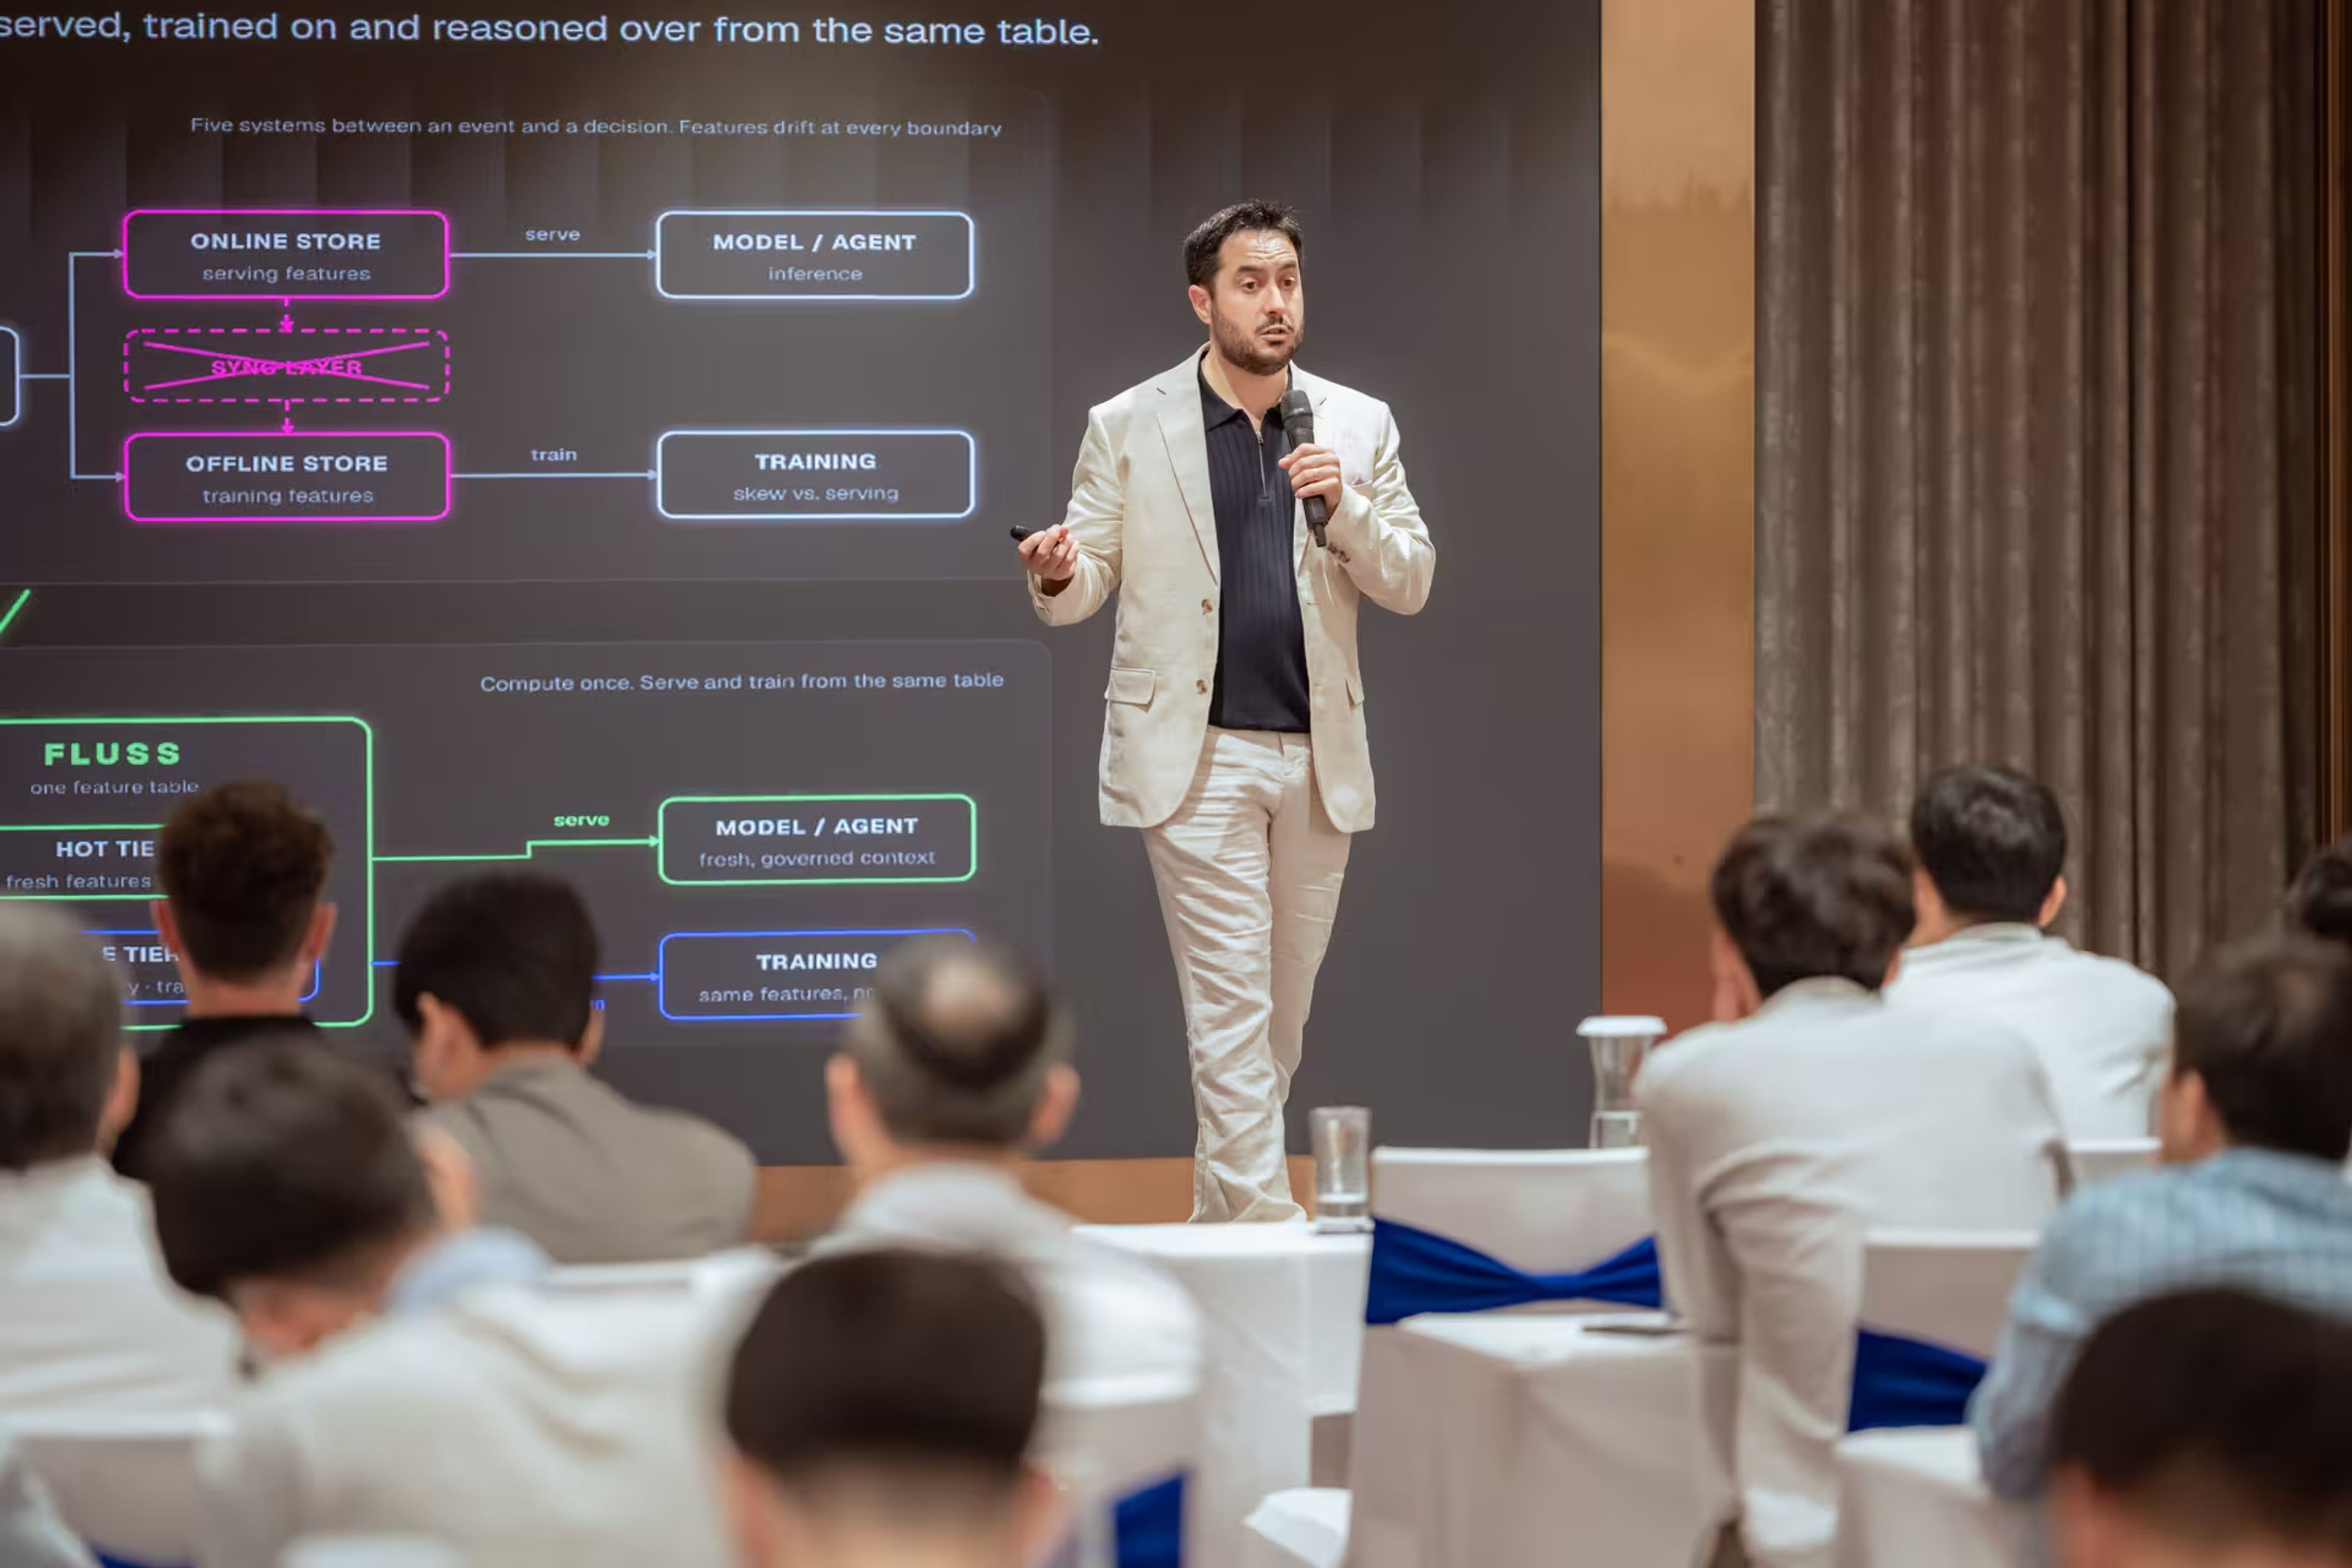
The big reason behind it is, of course, AI. A person reading yesterday's report knows to adjust for it. An AI agent approving a loan, blocking a payment or answering a customer will treat the data it receives as the most current, trusted state of affairs. An agent does not absorb the freshness gap: it acts on it. This means that stale data stops being a performance problem, and it becomes a correctness problem. If the fraud score is outdated, the agent may clear a payment that later turns out to be suspicious. A bank that deploys agents in production will need data that is current, governed and consistent across every system that reads it.
In the same week, we sat down with the CIOs and CTOs of several of Vietnam's largest banks. Three themes came up in almost every conversation.
The front end is no longer the bottleneck. Digital channels already carry the overwhelming majority of transactions. The pressure has moved to the data platforms behind them, which were designed for end-of-day reporting and are now expected to support decisions in milliseconds.
AI ambition is running ahead of data foundations. Every leader we met wants AI in credit, fraud and customer service. Leaders who are responsible for business-critical applications cannot go to production until the data feeding them is fresh, governed and trusted by the risk function.
Control matters as much as speed. With the new Personal Data Protection Law in force since the beginning of 2026 and security a board-level priority, banks want platforms they can run in their own cloud accounts and data centres, on open formats, with local partners who can support them in delivering results.
Taken together, these conversations point to the main conclusion Chris and I made from the trip: Vietnam's banks have won the race to the customer. The next race is for the data behind every decision.
BNH's view: the Vietnamese banks of the future are being built today
by Linh Nguyen, CEO of BNH
Under Vietnam's National Digital Transformation Strategy for 2026–2030, we are not just witnessing targets like a 30% digital GDP or cashless transactions exceeding 30 times our national output: we are on the ground, helping our private sector architect them. These are not just metrics for IT teams; they are the blueprint for a nation that moves at the speed of real-time events. As a local leader delivering this transformational technology across Vietnam, we see this as our defining moment to elevate our banking ecosystem onto the global stage.
We see three shifts happening by the end of the decade:
- The bank becomes real time end to end: credit, risk limits, liquidity and reporting follow payments and authentication, because customers and supervisors will stop accepting answers that depend on when the batch last ran.
- AI agents become ordinary bank staff, and the banks that earn customers' trust will be the ones whose agents see the same current, governed data as their best employee.
- And this capability gets built here, in Vietnamese banks' own clouds and data centers, run by Vietnamese engineers.
BNH's role is to make that practical, with local expertise, delivery, training and a direct line to the world’s top experts in real-time, mission-critical systems; which in this case could only mean Ververica.
Apache Flink® and Apache Fluss™ are trademarks of the Apache Software Foundation.